Health Insurance Before 2027 8 Things to Review in India

A policy that felt sufficient two or three years ago may not match hospital bills in 2026. Room charges, procedure costs, diagnostics, consumables and post-hospital care can change faster than a health cover if it is renewed without review.
A year-end health insurance coverage review is not about buying the largest policy available. It is about checking whether your present cover still fits your age, city, family size, medical history and likely hospital choices. This guide covers the eight areas Indian policyholders should review before 2027, without repeating basic health insurance definitions.
This article is for general information only. For policy decisions, read your policy wording and speak to a licensed insurance advisor.
Why a year-end health policy checkup matters before 2027
Healthcare costs in India are rising across metros, tier-2 cities and specialist hospitals. A short admission for dengue, appendicitis or a planned surgery can involve more than the surgeon’s fee. The bill may include room rent, investigations, implants, medicines, nursing charges, consumables and follow-up care.
That is why health insurance review 2026 India is a practical task, not just a renewal formality. Many disputes happen because policyholders assume all medical expenses are covered. The actual answer sits in the policy wording, especially under exclusions, waiting periods, room rent limits, co-payments and sub-limits.
Before renewing, download the latest policy schedule, policy wording, endorsements and renewal notice. Check what has changed since the last renewal.
1. Check whether your sum insured is still adequate
The first question is simple: Is my current health insurance enough? The answer depends on where you may seek treatment and who is covered.
A ₹5 lakh cover may look comfortable for a young individual in a smaller city, but it may feel thin for a family floater in Mumbai, Delhi NCR, Bengaluru, Pune, Hyderabad or Chennai. A family floater is shared by all covered members. If two people need hospital care in the same year, the available balance can shrink quickly.
Practical examples:
A young professional with no dependants may review whether a base policy plus top-up cover gives better protection than only a small employer policy.
A family with two children should check whether the floater sum insured can handle more than one claim in a year.
Senior parents may need higher cover because age-related admissions and longer hospital stays are more common.
A self-employed person should factor in both hospital bills and loss of income during recovery.
If your city, family size or preferred hospital category has changed, review your sum insured seriously before renewal.
2. Read room-rent conditions before assuming full claim payment
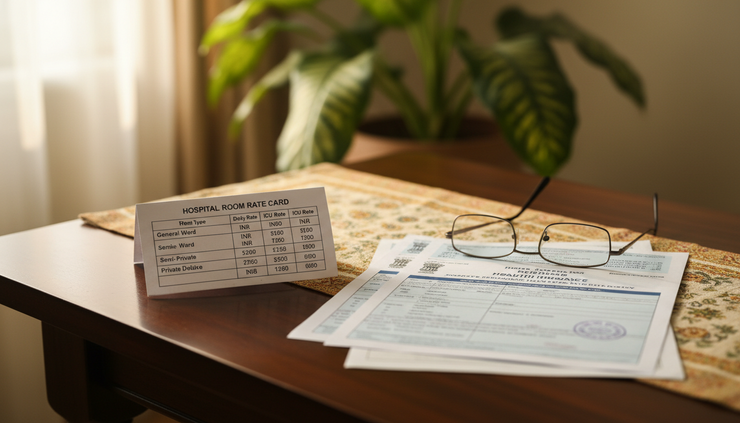
Room-rent limits can affect the whole claim, not just the room bill. Some policies allow any room up to the sum insured. Others restrict room rent by amount or percentage.
For example, if a policy allows a certain room category and the insured person chooses a higher category, proportionate deductions may apply to related charges. That can reduce claim payout even when the total bill is within the sum insured.
Check these terms in your policy wording:
Term to check | Why it matters |
Room rent limit | Can affect room eligibility and claim deductions |
ICU limit | Important for serious admissions |
Proportionate deduction | May reduce associated charges |
Room category wording | Defines whether single private room, shared room or other category is allowed |
3. Review co-payments and disease-wise sub-limits
A co-payment means the policyholder pays a fixed share of admissible claim costs. This is common in some senior citizen policies, lower-premium plans and policies bought with specific conditions.
Sub-limits are caps within the overall cover. They may apply to cataract surgery, maternity, modern treatments, ambulance charges, domiciliary treatment or specific procedures.
This is where many policyholders get surprised. A ₹10 lakh policy does not always mean every covered procedure is payable up to ₹10 lakh. The policy may have internal caps.
During your medical insurance review India, look for:
Co-payment percentage
Disease-wise or procedure-wise caps
Limits on modern treatments
Ambulance limits
Pre and post-hospitalisation day limits
Consumables or non-medical item treatment
4. Check network hospitals in your current city
Network hospitals matter because they support cashless claims, subject to approval and policy terms. Before 2027, check whether your preferred hospitals are still in the insurer’s network.
This is especially useful if you recently moved cities, changed jobs or started caring for parents in another city. A policy bought while living in Jaipur may not be convenient if treatment is now likely in Bengaluru or Gurugram.
Do not check only the number of network hospitals. Check the names that matter to you:
Nearby multi-speciality hospitals
Hospitals where your regular doctors practise
Good paediatric hospitals for children
Cardiac, oncology or orthopaedic centres for senior parents
5. Understand restoration benefits before relying on them
Restoration benefit can refill the sum insured after it is used, but the details vary. Some plans restore only after full exhaustion. Some do not allow restored cover for the same illness in the same policy year. Some restoration benefits apply only once.
For a family floater, restoration can be valuable. Suppose one family member uses most of the sum insured for surgery. A restoration feature may protect the rest of the family for another unrelated claim, if the policy conditions allow it.
Read the exact wording. Do not assume restoration means unlimited cover.

6. Look at claim history and renewal changes
Before renewing, review last year’s claims. Were deductions applied? Were consumables unpaid? Did the insurer ask for extra documents? Was cashless approval smooth?
Claim history gives clues about whether your current plan matches your needs. If repeated deductions occurred because of sub-limits or non-payable items, renewal is the right time to compare alternatives or add suitable covers.
Also check the renewal notice for changes in premium, terms, loading, exclusions or endorsements. If you are porting the policy, start early. Portability usually requires time before the renewal date and depends on underwriting rules.
7. Revisit exclusions, waiting periods and policy wording
This is the most overlooked part of health insurance planning. Exclusions are not small print to skip. They decide what will not be paid.
Check these areas carefully:
Permanent exclusions
Initial waiting period
Pre-existing disease waiting period
Specific disease waiting periods
Maternity and infertility-related exclusions or limits
Dental, vision and OPD terms
Consumables and non-medical expenses
Mental health and modern treatment wording
The key rule is clear: read the current policy wording, not only the brochure or sales summary. Policy wording is the contract. It explains the boundaries of your cover.
8. Update cover after changes in family circumstances
Your health cover should change when your life changes. Before 2027, review your policy if any of these happened:
Marriage
Childbirth or adoption
Parents becoming financially dependent
Change from employee to self-employed
Move to a different city
Diagnosis of a chronic condition
Change in income or hospital preference
A young professional relying only on employer cover may need personal insurance because job changes can create gaps. A self-employed consultant may need stronger personal cover because there is no employer group backup. A family with a newborn should check when the child can be added and what waiting periods apply. Senior parents may need careful review of co-payments, room limits and exclusions before renewal.
Quick answers for policyholders before renewal
How should I review my health insurance?
Start with the policy schedule, then read the policy wording. Check sum insured, room rent, co-payments, sub-limits, exclusions, network hospitals, restoration and claim experience.
Should I increase my sum insured?
Consider increasing it if your cover is shared by family members, you live in a high-cost city, you have senior parents covered, or your current sum insured would not comfortably cover a major admission.
What health insurance terms should I check?
Focus on room rent, proportionate deduction, co-pay, sub-limits, waiting periods, exclusions, restoration benefit, pre and post-hospitalisation cover, and cashless hospital network.
What should I check before renewing health insurance?
Check whether the premium, benefits, exclusions, claim conditions or family details have changed. Also confirm that your preferred hospitals remain in the cashless network.
Start 2027 with the right level of protection
A good year-end health policy checkup can prevent unpleasant surprises later. The aim is not to guess future medical bills. The aim is to make sure your current policy is not outdated for your family, city, age and health needs.
Start 2027 with insurance protection that matches your current needs. TrustCare Insurance helps individuals and families across India understand their health insurance options, compare suitable choices and review cover before renewal.
Comments