Insurance Nominee Guide for Indians Who to Nominate and Why It Matters

A policy can be active, premiums can be paid on time, and the claim can still get delayed because one small field is wrong: the nominee name.
In India, a nominee is the person named in an insurance policy to receive claim money or help complete claim formalities if the policyholder dies. This sounds simple, but the practical impact is huge. Outdated nominee details can create confusion, disputes, extra paperwork, or delays for the family at the worst possible time.
This guide explains insurance nominee India basics across life, health, motor, and other policies. It is informational only and not legal advice. Nominee rights and claim processes can vary by product, insurer, policy wording, and applicable law.
What an insurance nominee does
An insurance nominee is the person recorded in the policy to receive the claim amount or represent the policyholder’s interest after death. The nominee gives the insurer a clear person to contact and pay, subject to documents and policy terms.
For example, in a life insurance policy, the life insurance nominee is usually the person who files the death claim and receives the payout after the insurer approves it.
A nominee is not always the final legal owner of the money in every situation. In some cases, the nominee may receive the amount on behalf of the legal heirs. In life insurance, Indian nomination rules have specific provisions, including the concept of a beneficial nominee for close family members in certain situations. That means the result can differ based on who is nominated and what the law says at the time of claim.
A safe way to think about it is this:
Policy detail | What it helps with |
Correct nominee name | Helps identify the claimant |
Relationship with nominee | Reduces confusion during verification |
Updated address and contact | Helps the insurer reach the right person |
KYC documents | Supports faster claim processing |
Appointee for minor nominee | Allows an adult to act until the minor becomes eligible |
Why nominee details matter so much
Nomination is not just a formality. It can decide how smooth or stressful the claim process becomes.
If nominee details are correct, the family usually knows who should approach the insurer, what documents to collect, and how to begin the claim. If details are missing or outdated, the insurer may ask for extra proof, legal heir documents, succession-related papers, or clarification from family members.
Outdated nomination creates common problems:
A parent remains the nominee even after marriage, while the spouse is unaware of the policy.
An ex-spouse is still recorded after divorce.
A nominee has died, but the policy was never updated.
A child is born, but financial planning documents still name only one older family member.
The nominee’s name spelling does not match Aadhaar, PAN, or bank records.
The nominee’s bank account is inactive or unavailable.
These issues do not always block a claim, but they often slow it down. In sensitive cases, they may lead to disputes among family members.

Who should you nominate in different insurance policies
The right nominee depends on the purpose of the policy and the people financially affected by the policyholder’s death.
Life insurance
For life insurance, nominate the person or people who depend on the policy proceeds. This may be a spouse, children, parents, or another close family member.
If the nominee is a minor, name an appointee. The appointee is an adult who can receive or manage the claim process until the minor is legally capable. Without an appointee, the claim can become more complicated.
You can also nominate more than one person in many policies and specify percentage shares, depending on the insurer’s process and policy rules.
Health insurance
A nominee in health insurance becomes relevant mainly when a reimbursement claim or policy benefit needs to be paid after the insured person’s death. In cashless hospitalisation, the insurer usually settles directly with the hospital, so the nominee may not play the same role.
For family floater policies, check who is the proposer, who is insured, and who is nominated. These details can matter during claim settlement or refund of admissible amounts.
Motor insurance
In motor insurance, nomination may matter for own damage claims, policy transfer after the owner’s death, or settlement of certain benefits. Third-party injury or death claims follow separate legal processes and may involve legal heirs or tribunal proceedings.
Keep the vehicle registration, insurance policy, and nominee or legal heir documents aligned wherever possible.
Personal accident, travel, home, and other covers
Personal accident policies often rely heavily on nomination for death benefit claims. Travel insurance may need nominee or legal heir details if death or repatriation-related benefits arise. Home insurance may involve the owner, co-owner, lender, or legal heir depending on policy wording.
When you should update your nominee
You can usually change nominee after buying insurance. The process is called an insurance nomination change or nominee update. Insurers may call it an endorsement, service request, or policy servicing change.
Update insurance nominee details after major life events:
Marriage
Divorce or legal separation
Birth or adoption of a child
Death of an existing nominee
Death of an appointee for a minor nominee
Change in financial dependants
Family dispute or change in personal wishes
Nominee name change after marriage or other legal update
Change in address, mobile number, email, or bank account
Estate planning changes, such as a will
If your nominee dies before you, update the policy as soon as possible. If the nominee dies and no new nominee is recorded, the claim may need to be made by legal heirs or representatives with additional documents.
How to change your insurance nominee
If you are wondering how to change insurance nominee details, the usual process is straightforward.
Contact the insurer or advisor
Ask for the nominee change form or check the insurer’s customer portal.
Fill in the new nominee details
Include full name, relationship, date of birth, address, mobile number, email, and share percentage if there are multiple nominees.
Add an appointee if the nominee is a minor
Provide appointee details and relationship with the minor.
Submit identity and policy documents
The insurer may ask for policy number, identity proof, address proof, and signed request.
Get written confirmation
Do not rely only on a submitted form. Keep the endorsement, confirmation email, or updated policy schedule safely.
Tell the right people
A nominee cannot file a claim if they do not know the policy exists. Share basic policy information with trusted family members.
Keep in mind that insurance nominee rules India can differ between policies. Always check the insurer’s process and the exact policy wording.
Practical nominee checklist for Indian policyholders
Use this checklist once a year, or after any major family event.
Check every insurance policy Life, health, motor, personal accident, travel, home, group insurance, and employer-provided covers.
Confirm nominee name spelling Match it with Aadhaar, PAN, passport, or other accepted documents.
Check relationship details Make sure the relationship is correct and current.
Review percentage shares If there are multiple nominees, confirm the share split adds up correctly.
Add appointee details for minors Choose a trusted adult and keep their details updated.
Update contact information Mobile number, email, and address should be usable.
Store documents safely Keep policy bonds, e-policy copies, premium receipts, and claim process notes in one place.
Inform the nominee Share insurer name, policy number, and where documents are stored.
Review after life events Marriage, divorce, childbirth, death, and major dependency changes should trigger a review.
Keep proof of updates Save acknowledgements and endorsements from the insurer.
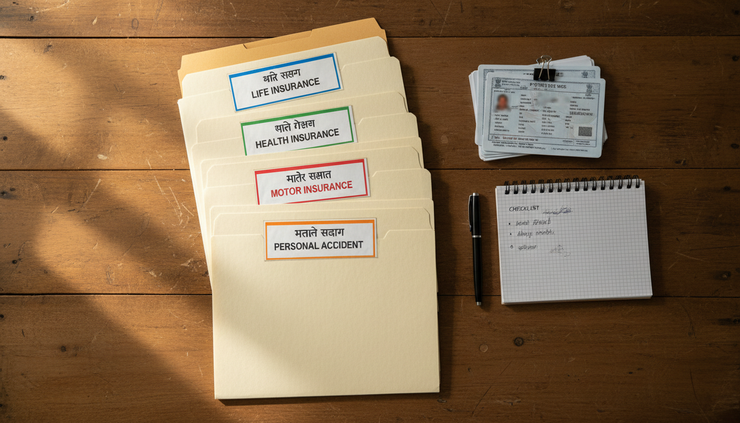
Your insurance should reflect your real life, not an old form filled years ago. A correct insurance policy nominee helps your family act quickly, reduces avoidable confusion, and supports a smoother claim experience.
Keep your insurance information as current as your life. TrustCare Insurance can help you understand policy servicing and insurance documentation requirements. Review your nominees now, then set a yearly reminder to do it again.
Comments